

UNest: Invest & Save for Kids
3.8

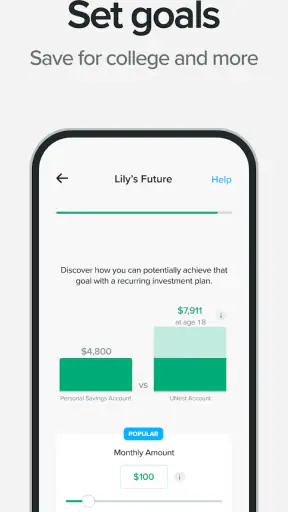
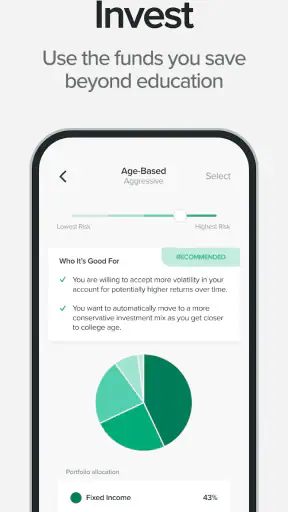
I found UNest: Invest & Save for Kids most useful when I treated it as a simple starting point for family investing rather than a complete financial planning service. Its central idea is easy to understand: help an adult save and invest for a child through a UTMA custodial account. That focus gives the app a clear purpose, and it makes the first step feel less intimidating than opening and managing a traditional investment account on your own.
At the same time, this is not an app I would recommend blindly to every parent or relative. A custodial account has real implications for how money is held and who eventually controls it, so convenience should not replace careful reading. My overall view is positive for families that want a guided, child-focused way to build a long-term habit, but more experienced investors may prefer a broader platform with greater control and more detailed planning tools.
What using UNest feels like in everyday family life
The strongest part of the experience is the way the app frames saving as an ongoing family activity instead of a one-time financial decision. Rather than asking a parent to understand every investment term before getting started, it puts the child at the center of the goal. That can make the idea of investing feel more tangible, especially for someone who has postponed it because conventional finance apps seem designed for professionals.
I can easily imagine using it after a child’s birthday or before a new school year. Instead of letting every gift disappear into ordinary spending, a family could decide that some money belongs to a longer-term goal. An adult can then use the account as a place to build that habit gradually. The useful shift is psychological: the app encourages the family to think beyond the next purchase without requiring the child to understand market mechanics immediately.
UNest Holdings, Inc. presents the product as a finance app, but its practical appeal is educational as much as financial. It gives parents a natural reason to talk about saving, patience, and the difference between money that is available now and money intended for later. Those conversations matter because an account alone will not teach good financial habits. The adult still has to explain what is happening and set realistic expectations.
The app is free to download, which lowers the barrier to trying the basic experience. There are also in-app purchases ranging from around five dollars to around one hundred fifty dollars per item. I would pay close attention to the cost of anything selected inside the app and compare that expense with the value of the service over the period I expect to use it. A low-friction sign-up can make a financial product feel cheaper than it really is if the ongoing cost is not considered carefully.
The custodial account is the important detail
The UTMA structure is not just a technical label. It affects the relationship between the adult, the account, and the child. The adult acts as custodian while the child is still a minor, but the money is intended for that child. That means I would not view the balance as a general-purpose emergency fund for the household. If a family needs complete flexibility to redirect savings later, a different account type may fit better.
This is also why I would set up the account with a specific intention in mind. Saving for education, early adulthood, or a first major financial step can lead to different expectations about timing and use. Even if the app makes the process approachable, I would still discuss the custodial arrangement with a qualified financial or tax professional when the decision involves a substantial amount of money or a complicated family situation.
One practical tip is to decide in advance whether contributions will come from the parent, relatives, or a mixture of both. That simple decision can prevent awkward confusion later. If grandparents or other family members want to participate, the adult managing the account should establish a consistent process for contributions rather than treating every gift as an improvised transaction.
Where the app earns its place
UNest works best as a behavior-building tool. Many people know that investing for a child can be sensible, yet they never move past researching options. A focused app can help turn that intention into a repeatable routine. I especially see value for a parent who wants to begin with modest, regular contributions and does not want to assemble a portfolio workflow from several unrelated services.
Its child-specific design also gives the account emotional visibility. A general brokerage account may be more flexible, but it can blend into the rest of an adult’s finances. A dedicated child-focused destination makes it easier to check progress during a family money conversation. That does not guarantee better returns, of course, but it can make the goal harder to forget.
Another strength is accessibility. The app is rated for Everyone, and it supports devices using Android 7.0 or later. The current version is 3.8.1, so users with older phones should check compatibility before planning around it. The age rating describes the app’s audience suitability, not the financial complexity of the account; an adult should remain responsible for understanding the arrangement and making decisions.
The product has reached more than one hundred thousand installs and holds an average rating of about 3.8 from roughly two and a half thousand ratings. I read that as a sign of a recognizable but not universally loved experience. It is enough adoption to suggest that the concept has found an audience, while the middling average is a reminder that ease of use and personal expectations will vary.
Three details I would handle before contributing
First, I would separate the app’s convenience from the investment result. A polished interface can make contributions feel productive, but market performance is not the same thing as app performance. I would decide how much risk and time horizon are appropriate before focusing on the balance display. For a child’s long-term goal, reacting emotionally to short-term changes could undermine the reason for opening the account.
Second, I would create a contribution rule that survives busy months. A fixed amount may be easy to remember, but a flexible schedule could be more realistic for families with irregular income. The best routine is not necessarily the most ambitious one; it is the one that can continue without forcing the household to withdraw money needed for rent, bills, or emergency expenses.
Third, I would keep a separate record of the account’s purpose, contributions, and relevant documents. Relying entirely on memory is risky when relatives contribute or when the child’s circumstances change. The app may make the account easier to manage, but good household organization still belongs outside the app. This is particularly important for families managing multiple children or coordinating money across households.
The main limitation: simplicity has a ceiling
The same focus that makes UNest approachable may feel restrictive once a user wants deeper control. Someone who already compares investments, understands account structures, or manages several financial goals may find a child-centered workflow too narrow. A conventional brokerage can offer a wider range of account types and a more unified view of household finances, even if it takes longer to learn.
I would also avoid assuming that a custodial investment account is automatically the best way to prepare a child for adulthood. The account is designed around the child, but the family may have other priorities first, such as paying down expensive debt, building an emergency reserve, or using an account with a different tax treatment. The right order depends on the household. A dedicated children’s investing app cannot solve a broader budgeting problem.
Cost deserves a second look here. Because the app is free to install but includes paid items, I would inspect the terms presented during setup and before purchasing anything. A fee can be reasonable if it replaces work I would otherwise struggle to do, but it becomes less attractive if I am paying for a narrow convenience while already having access to a suitable low-cost alternative.
There is also a human limitation that no interface can remove: investing takes patience. A parent who expects a quick, visible payoff may become disappointed when the account moves slowly or changes with the market. I would use the app only with a long-term mindset and would avoid presenting the balance to a child as guaranteed money. The educational value is stronger when the family discusses uncertainty honestly.
How it compares with the usual alternatives
The most obvious alternative is opening a custodial account directly through a traditional investment provider. That route may offer more research, broader account management, and a stronger fit for an investor who wants to make detailed choices. The trade-off is that the adult has to navigate more terminology and take greater responsibility for comparing options. UNest is more appealing when guidance and focus matter more than maximum flexibility.
A regular savings account is easier to understand and keeps the balance stable, but it may not serve a long-range wealth-building goal in the same way an investment account can. It can be preferable for money needed soon or for a family that cannot tolerate market movement. I would not use UNest simply because the word “invest” sounds more ambitious; the time horizon and purpose should decide.
Another alternative is saving in the parent’s own account and deciding later whether to give the money to the child. That approach preserves adult control and can be useful when future circumstances are uncertain. However, it does not create the same dedicated custodial structure or child-specific focus. UNest makes more sense when the family is comfortable setting money aside specifically for the child rather than keeping every option open.
A broad personal finance app may also be better for someone whose main need is budgeting, debt tracking, and household cash flow. UNest is not the tool I would choose to manage an entire family’s financial life. Its value comes from narrowing attention to one purpose. That specialization is helpful for a focused goal, but it should not be mistaken for a replacement for a complete financial plan.
Who should use it, and who should skip it
I would recommend it to a parent or relative who wants a dedicated way to invest for a child, prefers a guided experience, and is willing to learn what a UTMA custodial account means before contributing. It is also a reasonable fit for someone who benefits from a visible, child-centered goal and needs help turning good intentions into a regular habit.
I would be more cautious if the family may need to reclaim the money, change the beneficiary, or use the funds for a purpose unrelated to the child. The custodial structure should be treated as a meaningful commitment, not a temporary label. I would also steer an experienced investor toward a broader provider if detailed investment selection, consolidated account management, or low-cost comparison is the top priority.
Families with immediate financial pressure should skip the app for now rather than invest money they may soon need. Building a child’s future is worthwhile, but it should not come at the expense of basic household stability. In that situation, a straightforward savings plan or emergency fund may be the more responsible first move.
For relatives, I would use it only after agreeing with the child’s parent about the purpose of the contribution. A well-intentioned gift can create confusion if nobody has discussed whether it is meant for education, adulthood, or general future use. The app can organize the destination, but family communication determines whether the gift is actually helpful.
My final assessment after weighing the trade-offs
UNest: Invest & Save for Kids succeeds because it gives a complicated subject a clear family context. I like that it encourages long-term thinking without presenting itself as a general-purpose money dashboard. The free entry point, child-focused purpose, and custodial account structure make it approachable for adults who might otherwise keep postponing the decision to invest.
My reservation is that approachable does not mean complete. Users still need to understand what they are committing to, check the cost of in-app purchases, and decide whether a UTMA account matches their family’s goals. The app cannot replace financial judgment, and its focused design may feel limiting once a user wants more control or a wider view of their finances.
With that in mind, I would recommend it as a practical first step for families that want a dedicated child-investing routine and value simplicity over customization. I would not recommend choosing it automatically over a traditional brokerage or savings account. The right reason to use it is not that it makes investing effortless, but that it makes a specific family goal easier to start and remember.
3.8
430.00 Reviews
Pros
- Automated investing makes regular contributions easy to maintain.
- Designed specifically for children’s future financial goals.
- Supports gifting contributions from family and friends.
- Clear goal-based approach helps track long-term progress.
- Can introduce children to saving and investing concepts early.
Cons
- Investment returns are not guaranteed and account values can fall.
- Fees may reduce returns
- especially on smaller balances.
- Availability and account rules may vary by state or location.
- Withdrawals may involve restrictions or affect the account’s tax benefits.
- Parents remain responsible for choosing suitable investment options.


